A deck of cards. Each with a number written on one side, facing down. Assume is large, and all numbers are distinct. The deck is well suffled. We want to get the largest number. The rules are: 1. Reveal one card at a time starting from top. 2. Stop at the current card or reveal the next card. 3. If you pass on a card, then you can't return to it.
Find a strategy with success probability .
Here is a strategy.
Reveal a certain proportion, say , of the cards and record the largest number you have seen.
Then stop if you see a number larger than .
Now we find the optimal . Let denote the numbers. Order statistics: .
If , .
If , , .
If , , .
General case: , .
So which is maximized when .
1 Basics of DTMC
Discrete-Time Markov Chain (DTMC)
. State space discrete. Then Markov Chain satisfies for all
For example, 1d random walk.
Transition probability.
Homogeneous if transition probability is irrelevant of . Denote .
Transition matrix.
For every , i.e. row sum is for every row.
Claim (Chapman-Kolmogorov Equation)
, . I.e. .
This claim shows that the -step is actually the matrix product.
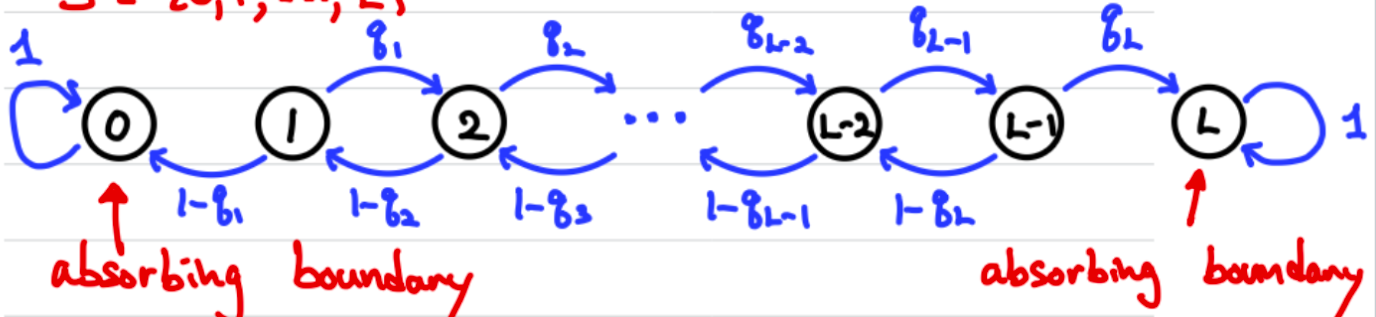
A graphical representation of a homogeneous Markov chain:
Some questions of interest: given ,
What is the probability of hitting before hitting ?
How long does it take?
How many times is state visited?
2 Classification of States
Accessible & Intercommunicate States
: state is accessible from if for some .
: states are intercommunicate if .
defines an equivalence relation.
The state space can be partitioned into equivalance classes of .
A subset is called irreducible if for all . is a strongly connected component (SCC). A Markov Chain is said to be irreducible if .
Some Important Values
First passage probability.
Return probability. (probability of finally coming back)
Mean recurrence time. (expected time of coming back)
State Definitions
A state is called
Recurrent/persistent if .
Null recurrent if .
Positive recurrent if .
Transient if .
Theorem
is recurrent s.t. , .
Recurrent is equivalent to visiting the state in infinitely many times.
is transitent . and .
3 Hitting and Recurrence
Suppose . We can't return from to (such are defined as absorbing states, and are transient). Then transition matrix can be written as
Hitting Probability
For , .
Claim
Proof: First-Step Analysis
Green part: . Yellow part:
In Matrix form, satisfies . Then if exists, .
Lemma
Suppose is a square matrix with . Then exists and .
Proof
So taking determinant:
Determinant is a continuous function, so
Plug this to (**), we have , then exists.
Back to . Since transient . So by lemma, exists.
Fundamental Matrix
is called the fundamental matrix of the absorbing Markov Chain.
Claim (Hitting Time)
Let be expected number of steps it takes to hit given . Then
Proof
First, note that , where for ,
In matrix form , we have . So is th row of .
4 Stationary Distribution
Stationary Distribution
The row vector is called a stationary distribution of the Markov Chain with transition probability matrix , if
.
. (i.e. is the left eigenvector of with eigenvalue .)
If , then .
Does every Markov Chain has a stationary distribution? When it exists, is it unique?
Theorem (Perron-Frobenius)
Every Markov Chain with finite has a stationary distribution .
If in addition the chain is irreducible, then is unique, and , where is the mean recurrence time for state .